Salary calculation looks simple until the edge cases arrive: an employee who joins mid-month, a resignation on the 20th, unpaid leave, overtime on a public holiday. Each has a prescribed calculation method under Malaysian law, and getting them wrong produces either an overpayment you cannot easily claw back or an underpayment that becomes a Labour Department complaint.
This guide covers the four calculations every Malaysian employer needs to perform correctly: prorated salary for incomplete months, the ordinary rate of pay, overtime rates, and net salary after statutory deductions — with worked examples you can check against your own payroll.
1. Prorated Salary for an Incomplete Month
When an employee joins, resigns, or takes unpaid leave partway through a month, wages are paid in proportion to the period worked. The widely used calendar-day method is:
Prorated salary = Monthly salary ÷ Number of days in the month × Number of eligible days (including rest days and public holidays falling within the employment period).
Example: an employee on RM3,100 per month joins on 16 June. June has 30 days, and the employee is employed for 15 of them. Prorated salary = RM3,100 ÷ 30 × 15 = RM1,550.
Whichever method your company adopts, apply it consistently and state it in your employment contracts or policies — inconsistency between employees is what turns a calculation choice into a dispute.
2. Ordinary Rate of Pay (ORP): The Basis for Everything Else
The Employment Act defines the ordinary rate of pay for monthly-rated employees as the monthly wages divided by 26. The ORP is the foundation for overtime, rest day pay, public holiday pay, and payment for annual leave encashment, so an error here multiplies into every other calculation.
- Daily ORP = Monthly wages ÷ 26
- Hourly rate = Daily ORP ÷ normal hours of work (typically 8)
Example: for a monthly wage of RM3,120, the daily ORP is RM3,120 ÷ 26 = RM120, and the hourly rate is RM120 ÷ 8 = RM15.
3. Overtime Calculation
Overtime under the Employment Act is paid at multiples of the hourly rate depending on when the work is performed:
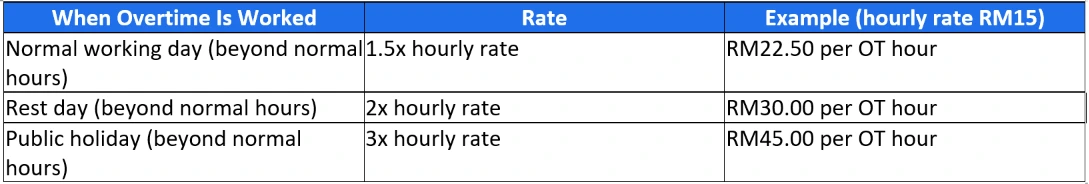
Work performed within normal hours on a rest day or public holiday attracts separate payment rules on top of these overtime multiples — a rest day worked on the employer’s request carries additional wages, and work on a paid public holiday entitles the employee to extra days’ wages before any overtime begins. Since the minimum wage moved to RM1,700, every one of these figures has risen for affected employees, because they all derive from the ORP.
4. From Gross to Net: The Deduction Sequence
Once gross pay is settled (basic + allowances + overtime + bonus), apply statutory deductions to reach net pay:
- EPF — employee share of 11% for Malaysians and PRs (2% for foreign workers), using the Third Schedule amounts rather than a straight percentage for wages below RM20,000.
- SOCSO — employee share of 0.5%, per the PERKESO contribution table, on wages capped at RM6,000.
- EIS — employee share of 0.2%, Malaysians and PRs only, also capped at RM6,000.
- PCB/MTD — income tax per LHDN’s schedule, based on the employee’s salary, marital status, children, and reliefs.
- Other authorised deductions — for example, approved salary advances or zakat, within the limits allowed under the Employment Act.
Worked example: net salary on RM3,100 gross
For a single Malaysian employee earning RM3,100 with no overtime: EPF employee share RM341 (Third Schedule band), SOCSO approximately RM15.25, EIS approximately RM6.10, and PCB close to zero at this income level for a single resident with standard reliefs. Net pay lands at roughly RM2,737. The employer separately bears its own EPF (about RM403 at 13%), SOCSO, and EIS shares on top — which is why the true cost of a RM3,100 employee is closer to RM3,560 per month.
Common Salary Calculation Mistakes
- Using calendar days for ORP instead of the statutory divisor of 26, which understates overtime and holiday pay.
- Prorating with different methods for joiners and leavers, creating inconsistency that surfaces in disputes.
- Deducting unpaid leave using a different day-rate than the one used for prorating salary.
- Calculating EPF as a straight percentage instead of using the Third Schedule amounts.
- Forgetting that allowances and overtime cannot count toward the RM1,700 minimum wage floor.
- Applying EIS deductions to foreign workers, who are not covered by the scheme.
Let the System Do the Arithmetic
None of these calculations is difficult in isolation. The risk comes from volume and variation — dozens of employees, joiners and leavers every month, overtime across different day types, and statutory tables that change with each Budget. AI HCM performs every calculation in this guide automatically: prorating on your chosen policy, ORP-based overtime by day type, Third Schedule EPF, SOCSO and EIS tables, and current-year PCB — all flowing from the same attendance and leave records, with an itemised e-payslip at the end. Book a free demo and compare it against your current month-end.
Disclaimer: This article is for general information only and is not legal, tax or professional advice. Statutory rates, rules and product specifications in Malaysia can change. The information is accurate as of the date the article was published or last updated. Check the latest guidance from the relevant authority, or speak to a qualified adviser or our team, before making decisions.